Nebius Asset-Light Business Model: The Cloud Someone Else Pays to Build
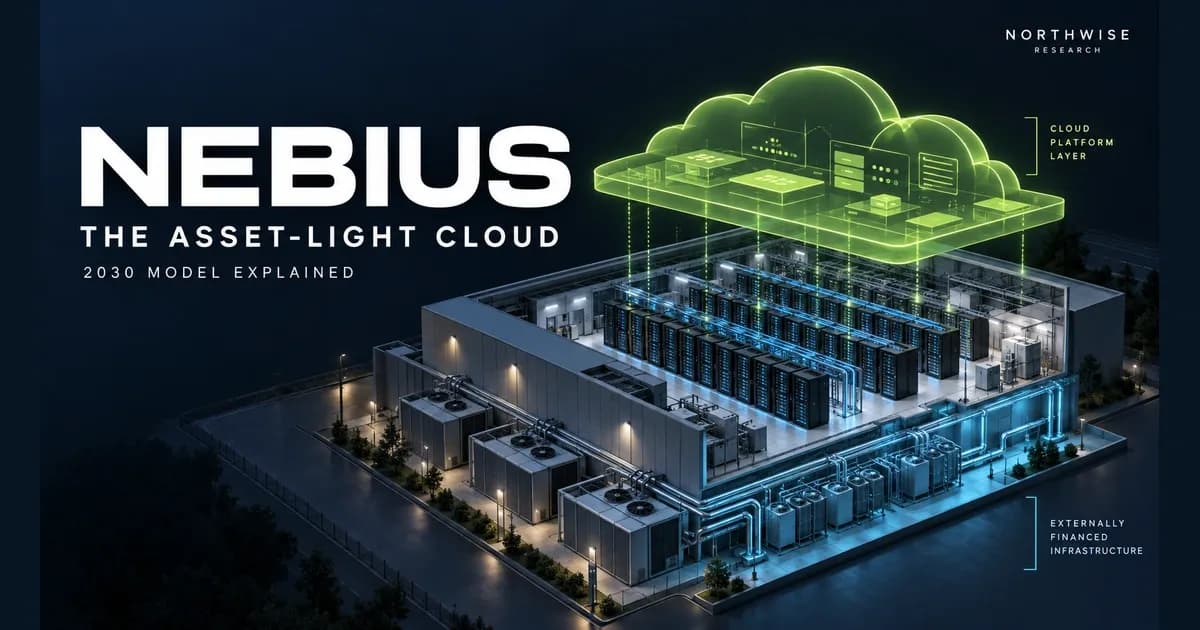
How Nebius can earn cloud fees on partner-owned GPUs. Explore owner economics, Palantir, cash flow and our 2030 asset-light scenarios in this free report.
Nebius
Northwise Research
Filtered research
How Nebius can earn cloud fees on partner-owned GPUs. Explore owner economics, Palantir, cash flow and our 2030 asset-light scenarios in this free report.
IREN stock analysis of AI growth, funding and dilution through 2030. Read our full valuation, 27 scenarios and price zones free. Excel model is Premium.
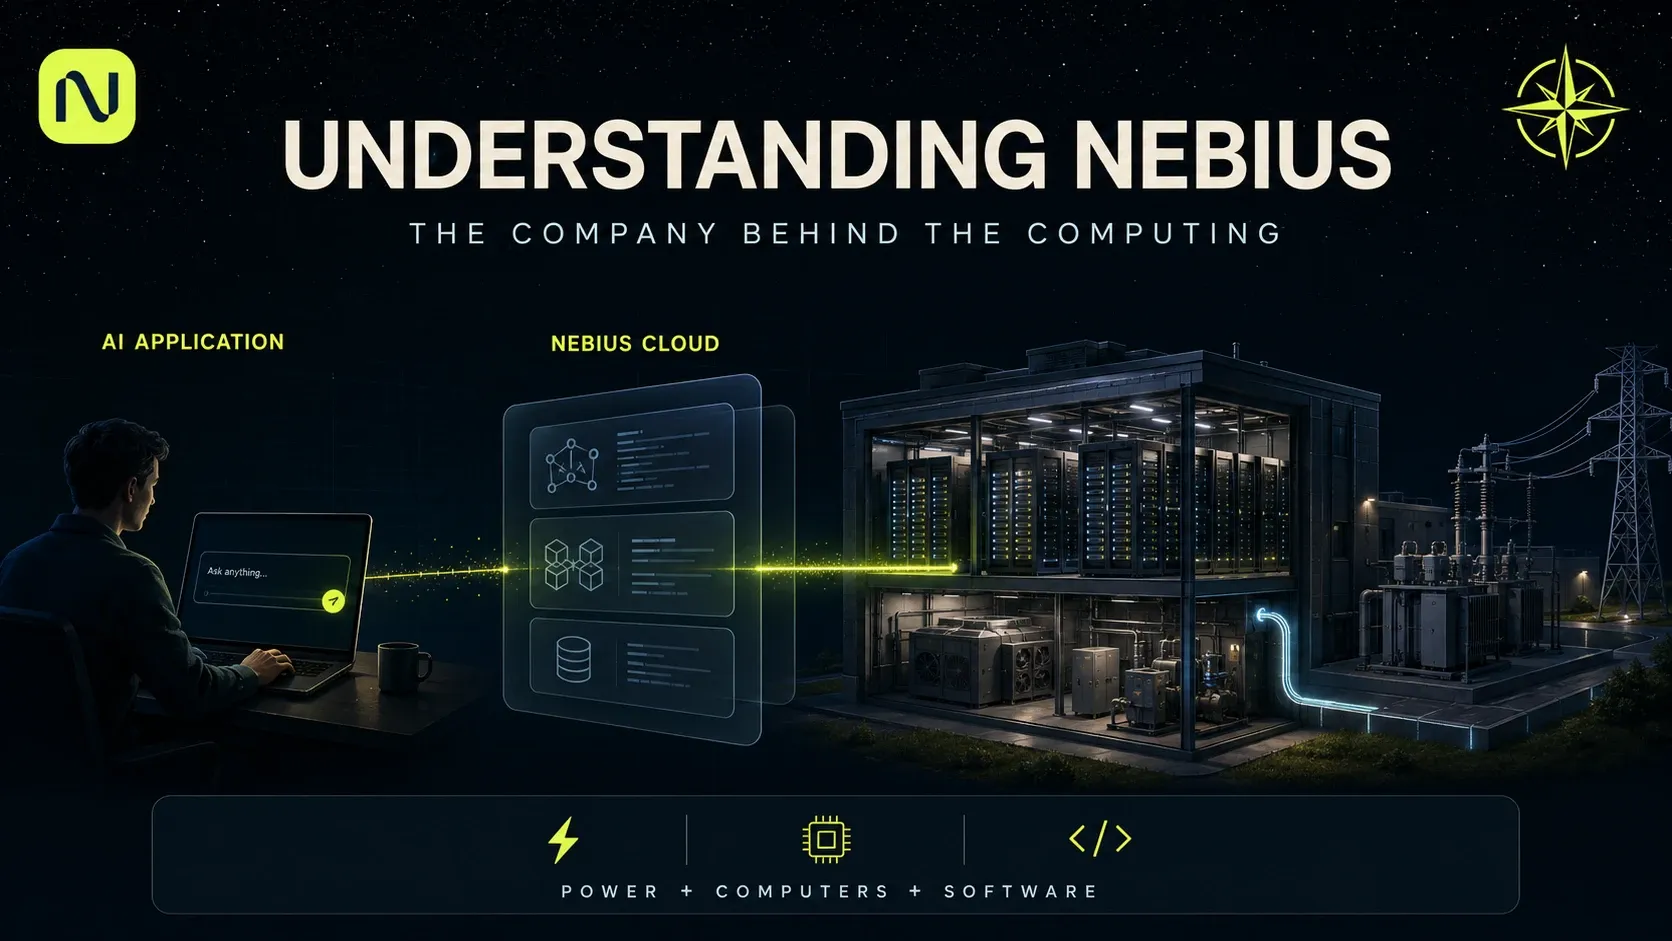
Understand Nebius from the ground up: its AI cloud, competitors, subsidiaries, funding, and growth opportunities. A complete NBIS guide with 14 illustrations.
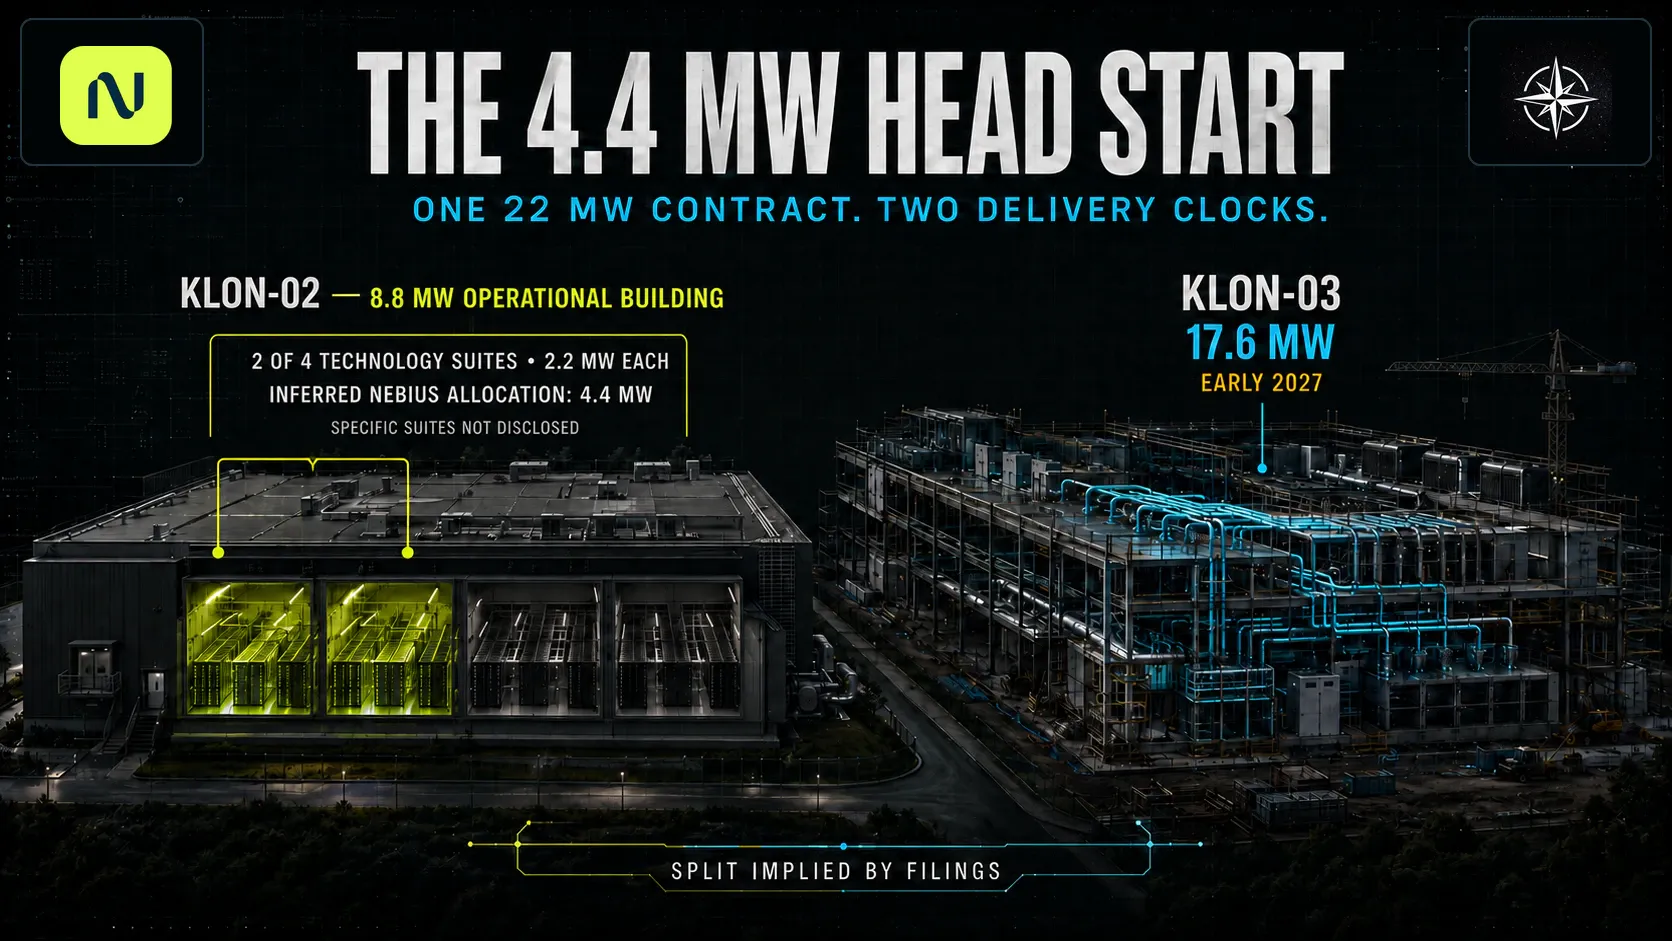
How European AI sovereignty supports Nebius’s UK expansion, where Harlow fits, and what its potential 4.4 MW deployment could add to Q3 revenue and 2026 ARR.
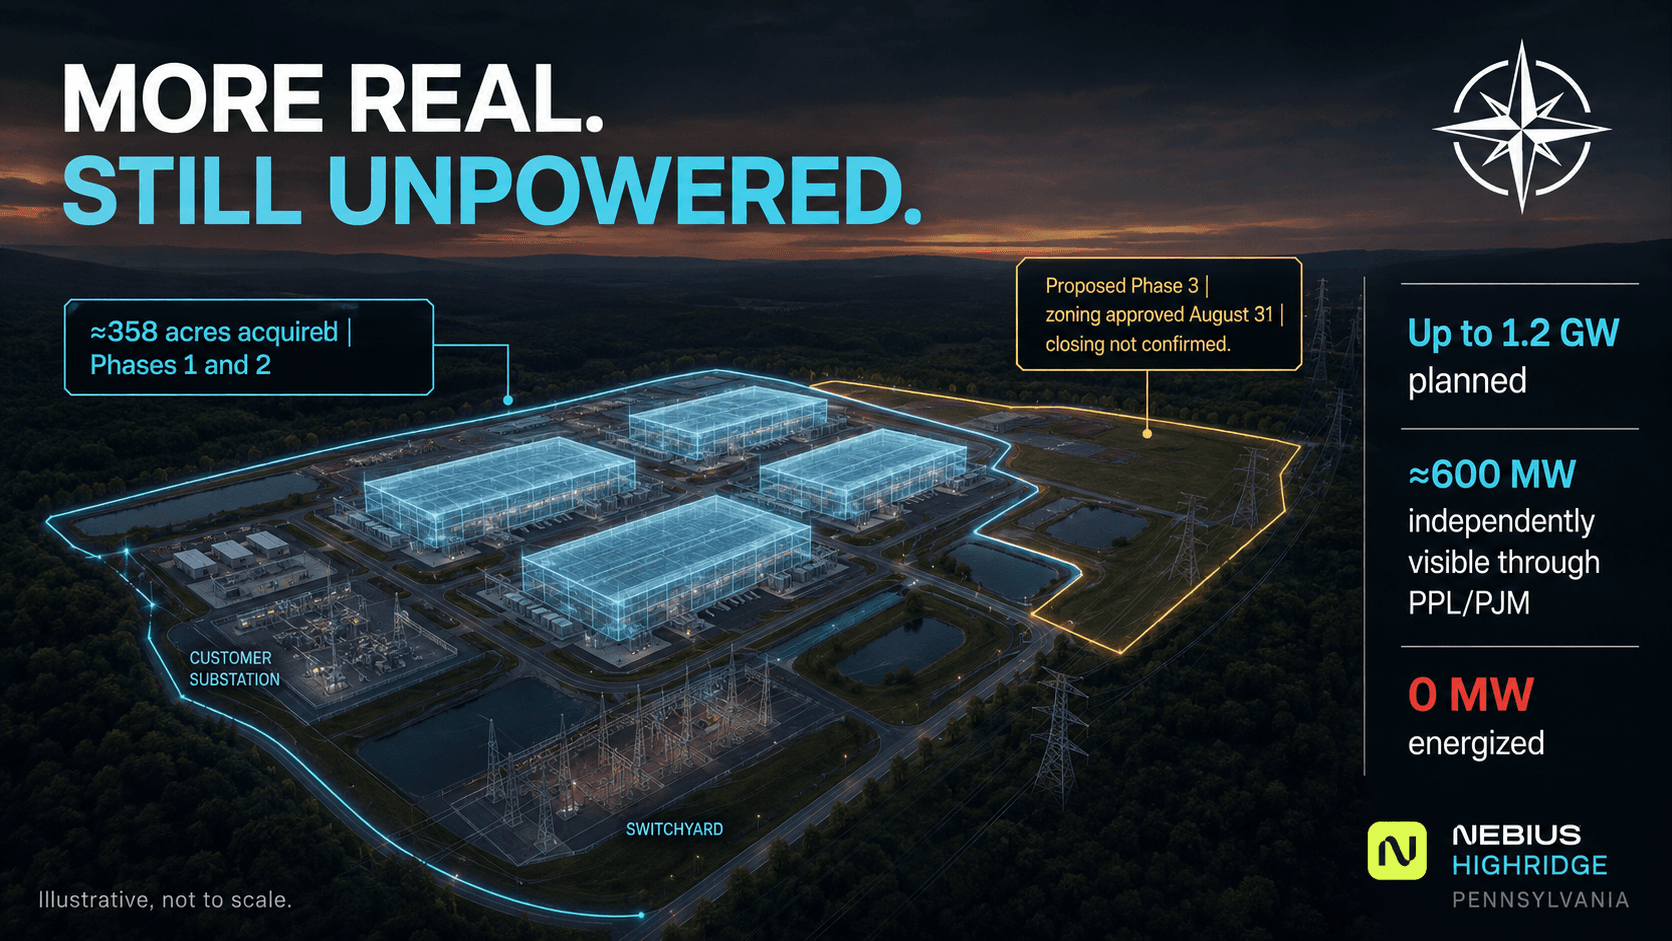
Nebius has cleared the zoning gate for the full planned Highridge footprint. The back half is more credible, but final land, development, and grid approvals still separate 1.2 GW from reality.
IREN’s new AI-developer contracts are the strongest evidence yet that it can sell something more valuable than bulk hyperscaler capacity.
Explore IREN data centers in Canada, the US, Australia and Spain, with site studies and clear distinctions between planned power and delivered AI capacity.
NBIS Stock Forecast 2030: A complete Nebius analysis covering AI capacity, Nvidia, contracts, CapEx, prepayments, revenue, margins, funding, & valuation.
Barber Lake: Fluidstack's contracted capacity, phased delivery, Google's support and the September update on Colorado City's water infrastructure.
Black Pearl: initial AWS capacity delivered and rent begun, remaining construction, the lease structure and the limits of the public technical record.
TeraWulf's current portfolio: Lake Mariner delivery, Anthropic at Justified, Kentucky power approval, later developments and changing site ownership.
Scrubgrass: legacy generation, the potential 1.3 GW campus and the power, environmental and commercial work still required.
Sherbrooke: the conditional consolidation of existing 96 MW into one planned AI campus, land conditions and 2028 service target.
Lappeenranta: the planned 310 MW Finnish AI campus, phased delivery and the distinction between design targets and operating capacity.
Sharon: the 110 MW gross development, delivered transformers, permitting progress and the path to a signed tenant lease.
Panther Creek: the 350 MW gross campus plan, legacy generation, current approvals and the remaining delivery milestones.
Longcross: Nebius's established UK deployment at Ark, purpose-built infrastructure and its place in the wider four-site programme.
Moses Lake: the 18 MW gross development, demolished mining building, delivered Vertiv modules and 2027 service target.
Kiowa, Oklahoma: IREN’s 1.6 GW planned power position, development timing and the remaining delivery dependencies.
Paris: Nebius's confirmed PA10 deployment and the distinction between cloud regions, host buildings and tenant allocations.
Cipher's complete named site portfolio, including Apollo, initial Black Pearl rent, contracted campuses and the remaining grid and generation pipeline.
Canal Flats: IREN’s 30 MW Canadian campus, existing infrastructure and planned liquid-cooled AI expansion.
Minnesota: Nebius documents Woodbury, while the Minneapolis property and 31 MW allocation in the earlier study remain unconfirmed.
From Bitfarms to Keel: the five development locations, current commercial stage, Moses Lake equipment progress and the funding questions ahead.