
IREN Stock Infrastructure Analysis
Explore IREN data centers in Canada, the US, Australia and Spain, with site studies and clear distinctions between planned power and delivered AI capacity.
In this article
IREN’s starting advantage was physical: land, electricity connections and campuses built to run large amounts of computing equipment. Moving from bitcoin mining into AI cloud services changes what must sit behind those connections. GPU servers need suitable cooling, networking, software and customer acceptance before a power position becomes useful AI capacity.
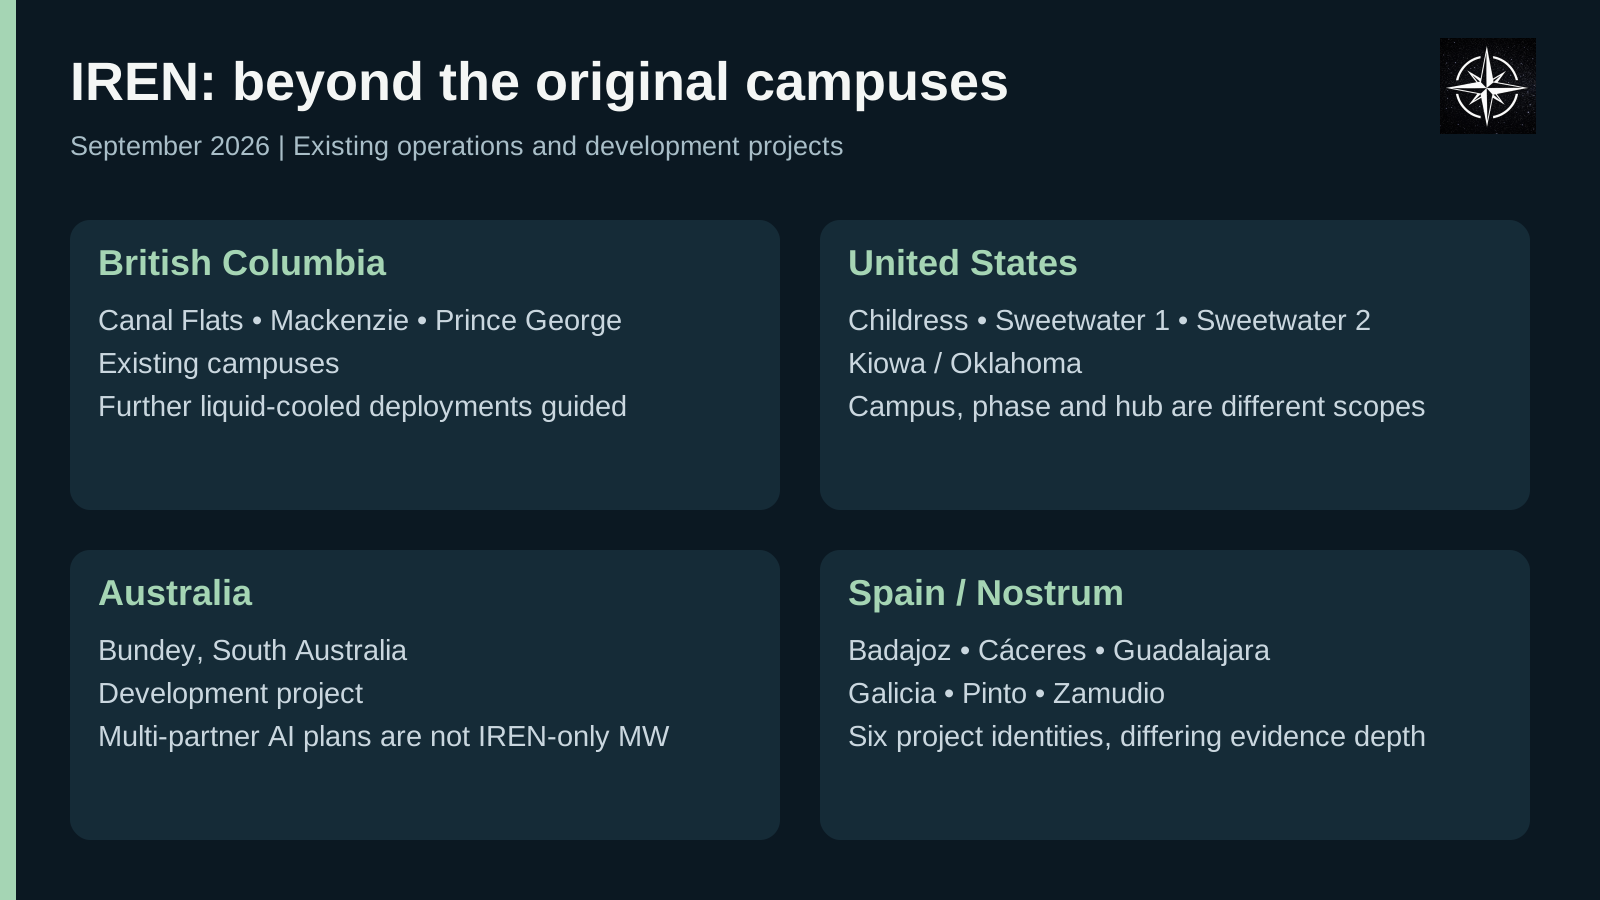
The company now spans its Canadian campuses, large US projects, an Australian development and an acquired Spanish portfolio. That wider footprint creates more places to build, while also increasing the number of construction and delivery milestones investors must follow. This guide brings the known projects into one current directory, with links to every existing Northwise site study and a clear distinction between project scale and delivered compute. Information is reviewed through September 17, 2026.
Explore the locations and their supporting evidence in the IREN Data Center Tracker. The directory below explains how the projects fit together.
The transition is visible at Childress
IREN’s August 27 results reported delivery of Horizon 1 to Microsoft, the first of four 50 MW IT deployments at Childress. Horizon 2 was commissioning, while Horizon 3 and 4 were in late-stage construction with delivery targeted for Q4 2026. Those stages show why the campus label alone is insufficient: several phases inside one property can be at different points in the delivery process.
The company also guided to approximately 0.3 GW of cumulative IT delivery in 2026 and 0.8 GW in 2027, with further liquid-cooled deployments planned at the three Canadian campuses. These are management targets, not Northwise forecasts or measurements of current utilization. The analytical question is how much of the power portfolio can move through construction, commissioning and customer delivery on the stated timetable.
Sources: IREN FY26 results, August 27
Power, IT capacity and delivery measure different things
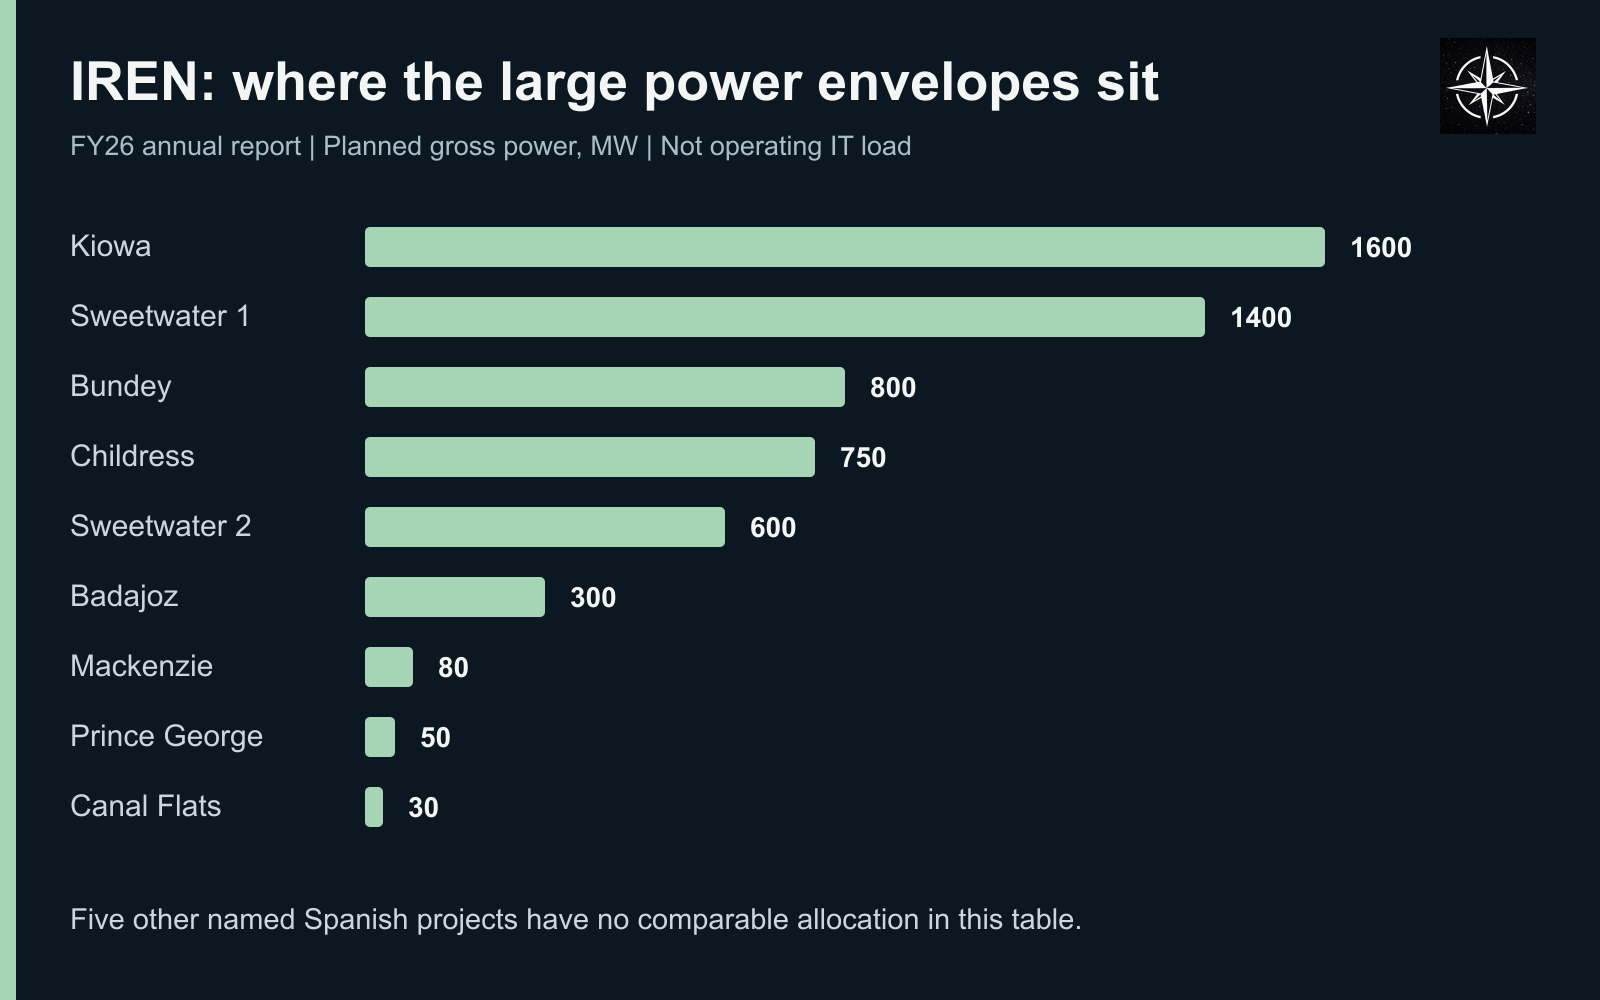
Gross power includes the electricity required to operate the facility, including cooling and other supporting systems. IT capacity concerns the computing equipment. A large campus envelope can support multiple future phases; it does not mean the entire site is built, equipped or earning revenue. Keeping these measures separate prevents a development portfolio from being mistaken for an operating fleet.
Sources: IREN FY26 annual report
The chart uses one consistent measure from the annual filing. Five further Spanish project identities appear in the directory without guessed shares of portfolio power. Sweetwater 1 and Sweetwater 2 belong to one hub, while the Horizon deployments are phases of Childress. Counting the hub or its phases again would inflate the footprint.
British Columbia
The Canadian campuses form the established base. Further AI deployments are expansions or conversions inside existing locations, rather than additional campuses.
Canal Flats, British Columbia
30 MW planned gross power in the FY26 filing. Existing campus with additional liquid-cooled deployment guidance for 2027.
Read the Canal Flats site study · IREN FY26 annual report; IREN FY26 results, August 27
Mackenzie, British Columbia
80 MW planned gross power. Air-cooled expansion and a further liquid-cooled deployment planned for 2027 are phases of this campus.
Read the Mackenzie site study · IREN FY26 annual report; IREN FY26 results, August 27
Prince George, British Columbia
50 MW planned gross power. Existing campus with further liquid-cooled deployment guidance for 2027.
Read the Prince George site study · IREN FY26 annual report; IREN FY26 results, August 27
United States
Childress is delivering AI capacity in phases, while Sweetwater and Kiowa represent larger development programmes. Each project needs its own status and power basis.
Childress, Texas
750 MW planned gross power. Horizon 1 was delivered to Microsoft as a 50 MW IT deployment. Horizon 2 was commissioning and Horizon 3-4 were in late construction in the August 27 update, targeting Q4 delivery. All four phases belong to Childress.
Read the Childress site study · IREN FY26 annual report; IREN FY26 results, August 27
Sweetwater 1, Texas
1,400 MW planned gross power. IREN reported that its high-voltage substation had been energized and that 300 MW gross of data center construction was progressing toward a Q4 2027 delivery target. The September 8 release describes conditional inclusion in ERCOT Batch Zero as base load; it does not establish completion of the whole project.
Read the Sweetwater 1 site study · IREN FY26 annual report; IREN Sweetwater update, September 8
Sweetwater 2, Texas
600 MW planned gross power. Sweetwater 2 is a separately identified project within the same 2 GW hub. Its conditional Batch Zero inclusion is a grid-process milestone. The hub is not a third campus to add to Sweetwater 1 and 2, and the announcement is not evidence of 2 GW of operating AI load.
Read the Sweetwater 2 site study · IREN FY26 annual report; IREN Sweetwater update, September 8
Kiowa / Oklahoma
1,600 MW planned gross power. Company development project, with future energization and compute deployment remaining separate milestones. Kiowa and the Oklahoma site report refer to the same project.
Read the Kiowa / Oklahoma site study · IREN FY26 annual report
Australia
Bundey adds a new geography to the portfolio. Australia-wide industry commitments should not be mistaken for capacity allocated entirely to IREN.
Bundey, South Australia
800 MW planned gross power in the annual filing. NVIDIA’s September 9 Australian initiative includes IREN; its multi-partner programme total is not an additional IREN site or an IREN-only capacity award.
A dedicated Northwise study is not yet available. IREN FY26 annual report; NVIDIA Australian infrastructure announcement, September 9
Spain: the Nostrum projects
The Spanish inventory includes six named projects. Badajoz appears in IREN’s main power table; disclosures from Nostrum and its adviser identify the other locations. The strength and detail of the evidence vary by project.
Badajoz / BAZ-01, Spain
300 MW planned gross power in IREN’s filing. Nostrum’s March disclosure targeted readiness to build in September 2026 and market entry in Q4 2027. These are dated targets, not confirmation that either milestone has occurred.
A dedicated Northwise study is not yet available. IREN FY26 annual report; Nostrum project update, March 13
Cáceres / CC Green, Spain
Named Nostrum development, also identified by its appointed adviser JLL. Retained as part of the acquired Spanish project inventory; no guessed site-level share of the portfolio’s power is assigned here.
A dedicated Northwise study is not yet available. JLL announcement for Nostrum, January 27
Guadalajara / GUA1, Spain
Nostrum announced 40 MWe granted at El Ruiseñor Industrial Park, targeting construction in late 2026 and operation in 2028. Electrical power granted is not delivered IT capacity.
A dedicated Northwise study is not yet available. Nostrum project update, March 13
Galicia / GAL1, Spain
Nostrum announced 25 MWe granted and a Q3 2027 operating target. Retained as an acquired development identity; the quoted schedule does not establish completed construction or active load.
A dedicated Northwise study is not yet available. Nostrum project update, March 13
Pinto, Spain
Named by JLL in its January 27 mandate for Nostrum’s six Spanish developments. Adviser-announced project identity, with current site-level capacity and delivery milestones unassigned in this directory.
A dedicated Northwise study is not yet available. JLL announcement for Nostrum, January 27
Zamudio, Spain
Named by JLL in the same Nostrum portfolio announcement. Retain the project and its adviser provenance without inventing a MW allocation or operating date.
A dedicated Northwise study is not yet available. JLL announcement for Nostrum, January 27
What Batch Zero changes
ERCOT Batch Zero is a grid-study process. IREN’s September 8 announcement conditionally includes the existing Sweetwater hub as base load and says other large-scale projects will enter its announced development portfolio after the relevant grid connection agreements are executed. It does not name a new campus called Batch Zero, and the conditional milestone is not equivalent to energizing the entire 2 GW hub.
Sources: IREN Sweetwater update, September 8
The execution questions behind the footprint
Our interpretation is that IREN’s power portfolio matters most when paired with a credible sequence for turning individual phases into service. An energized substation removes one dependency. A completed building removes another. Cooling systems, equipment, networking and customer acceptance still determine when the infrastructure can carry an AI workload.
The expanding geography also broadens the work required. Existing Canadian campuses have an operating base; a new Australian or Spanish development introduces local permitting, grid and construction dependencies. That makes project-level evidence more useful than treating every megawatt in the portfolio as equally close to revenue.
We will look for achieved delivery milestones, clearer site-level allocations across Spain, and confirmation of the next construction and grid steps at the larger developments. This guide describes the current infrastructure evidence. Published valuation models and forecasts remain separately dated research, accessible through the company page.
Continue the research
Use the IREN company page for the wider Northwise research library, company overview and separately published models. The filtered tracker below provides the location-by-location view.

IREN Stock Dilution: Can the Build Reach Shareholders?
IREN stock analysis of AI growth, funding and dilution through 2030. Read our full valuation, 27 scenarios and price zones free. Excel model is Premium.
IREN Stock Forecast 2030
IREN’s new AI-developer contracts are the strongest evidence yet that it can sell something more valuable than bulk hyperscaler capacity.

Iren Oklahoma Site
Kiowa, Oklahoma: IREN’s 1.6 GW planned power position, development timing and the remaining delivery dependencies.
Northwise Portfolios
See how the research becomes real decisions
Reader discussion
Discuss the research
Create a Free account to join the discussion with a display name.
Create a Free Account
No comments yet. Start a thoughtful discussion.