
S Stock Forecast 2030

S stock forecast 2030: Why we believe SentinelOne stock is a long-term cybersecurity AI compounder with misunderstood, undervalued upside.
In this article
S Stock Forecast 2030: Why We’re Long SentinelOne for the Next Decade
A long-view thesis on an underappreciated cybersecurity compounder, and why we think the market is missing the setup.
The Case for Looking to 2030
Short-term noise drives most market behavior, but the real opportunity often lies beyond the next quarter.
SentinelOne isn’t a momentum trade. It’s a structural bet. In a sector defined by reactionary spending and recurring fear cycles, SentinelOne is building something more deliberate.
We’re not trying to predict the next earnings beat. We’re positioning around long-term infrastructure that compounds quietly, and we think the market is mispricing that trajectory.
The cybersecurity landscape is evolving, but investor attention remains cyclical. Most flows follow fear, headline breaches, or quarterly surprises.
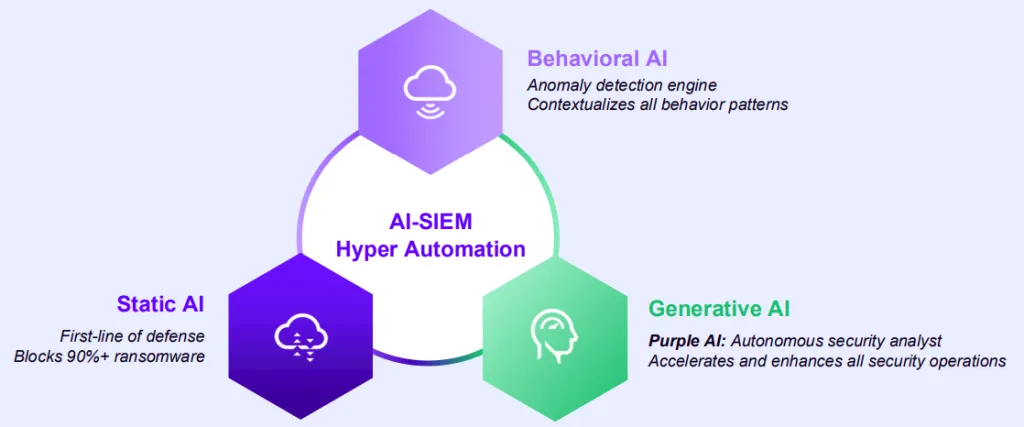
SentinelOne offers something different: a high-velocity platform with AI at its core, expanding quietly while the spotlight fades elsewhere. This is the kind of setup that doesn’t scream, but often compounds the loudest over time.
Expansion Economics and Embedded Value
SentinelOne’s ability to drive internal expansion is one of its most underappreciated strengths. With net revenue retention consistently over 110%, and at times reaching as high as 130% according to Morningstar, the company is showing real success in upselling customers into higher-value bundles.
This kind of stickiness is the foundation of compounding ARR, not just from landing new logos, but from growing wallet share within existing ones.
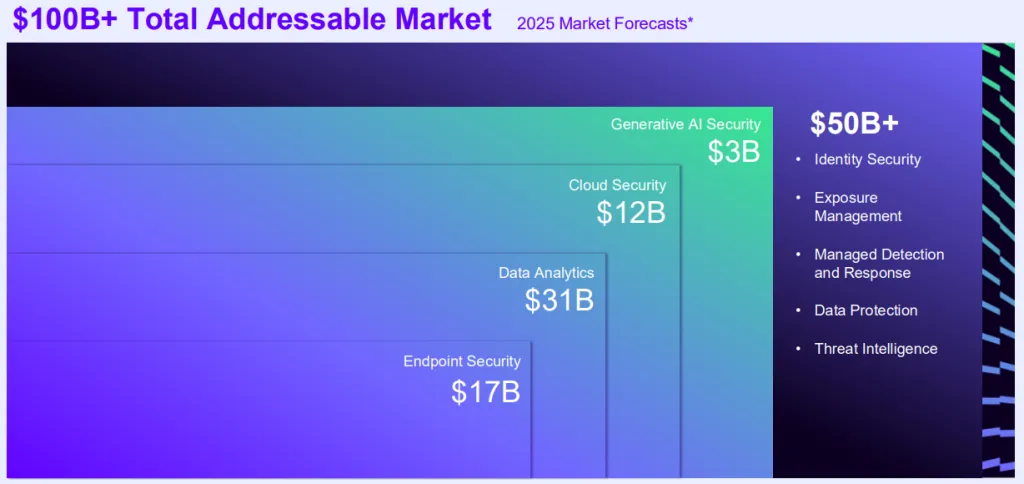
The platform’s modularity and AI-first design make it easy for clients to add services, whether that’s identity, cloud, or extended data visibility, without friction. Each additional module creates more surface area for value and makes it harder to churn.
Deal sizes are expanding, upgrade timelines are accelerating, and customer retention is improving. The product suite doesn’t just solve security problems, it embeds itself in workflows and expands from the inside out.
Built for Speed and Scale
SentinelOne’s Singularity Platform isn’t a feature set. It’s an architecture. Built from day one to prioritize automation, it delivers end-to-end security across endpoint, cloud, and identity layers: all without requiring human intervention at every step.
This unified foundation gives it an edge in environments that demand speed, integration, and proactive defense.
As the velocity and complexity of breaches accelerate, so does the need for platforms that can adapt at machine speed. Most enterprises today are managing a fragmented patchwork of tools. SentinelOne is working toward cohesion, an increasingly rare posture in a fragmented market.
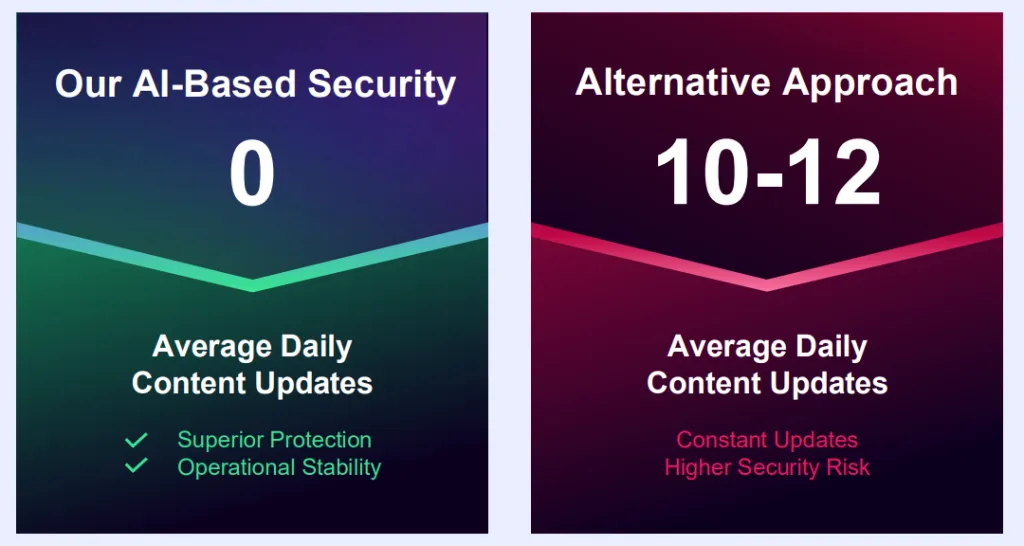
The platform’s modularity is a strategic weapon. It allows SentinelOne to meet clients where they are, whether that’s full XDR rollouts or lighter-weight endpoint deployments, while planting the seeds for deeper product expansion. Every foothold becomes a foundation.
AI Isn’t the Feature – It’s the Moat
There’s a meaningful difference between vendors that bolt on AI and those that are built around it. SentinelOne falls in the latter camp. Its modular platform leverages AI to continuously learn, respond, and reduce latency across its stack. In a field where seconds matter, that kind of reflexive architecture becomes a long-term advantage.
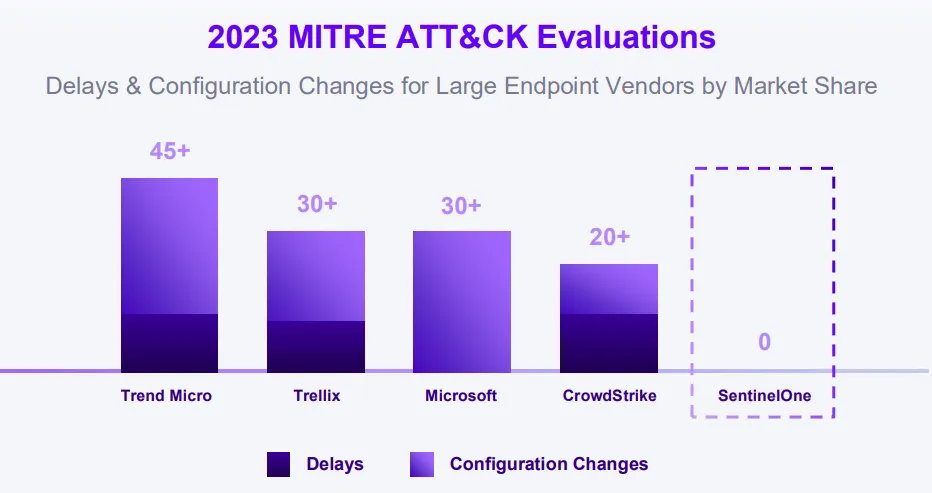
This isn’t about buzzword compliance. It’s about structural leverage. SentinelOne’s ability to deliver autonomous remediation, reduce analyst burden, and unify insights across threat surfaces is a result of its AI-first DNA, not a last-minute enhancement. Over time, this should result in both customer efficiency and operating leverage.
As enterprise security expands from endpoints to identities and cloud workloads, platforms that can move with those workflows, without introducing friction, will gain trust and traction. SentinelOne is building for that future now.
Q4 FY2025 Financials: Quiet Momentum, Real Leverage
The company’s Q4 FY2025 results reflect something most high-growth names lack: discipline.
- Revenue: $225.5M (+29% YoY)
- Annualized Recurring Revenue (ARR): $920.1M (+27% YoY)
- Non-GAAP Gross Margin: 80%
- EPS: $0.04 (adjusted)
This isn’t a burn-and-blitz story. It’s margin expansion, operational efficiency, and a top line that’s still growing nearly 30 percent. That combination, scale with margin, is rare in earlier-stage cybersecurity names.
SentinelOne also continues to show improving customer retention and larger enterprise expansion. With more than 10,000 customers globally, the company is moving upmarket, adding stickier, higher-value clients. That’s a flywheel we’ve seen before, and one that tends to strengthen as the platform matures.
Competitor Lens: CrowdStrike, Palo Alto, and the Sentiment Gap
CrowdStrike trades like it’s already won. SentinelOne trades like it’s already lost. Neither story is complete.
SentinelOne is catching up, on identity, on cloud, on product maturity, but without the bloat that comes with incumbency. CrowdStrike still leads in breadth and trust, but SentinelOne’s trajectory suggests that lead may not hold in perpetuity. It’s gaining ground in identity threat detection, and pushing into zero trust integrations at a pace few anticipated.
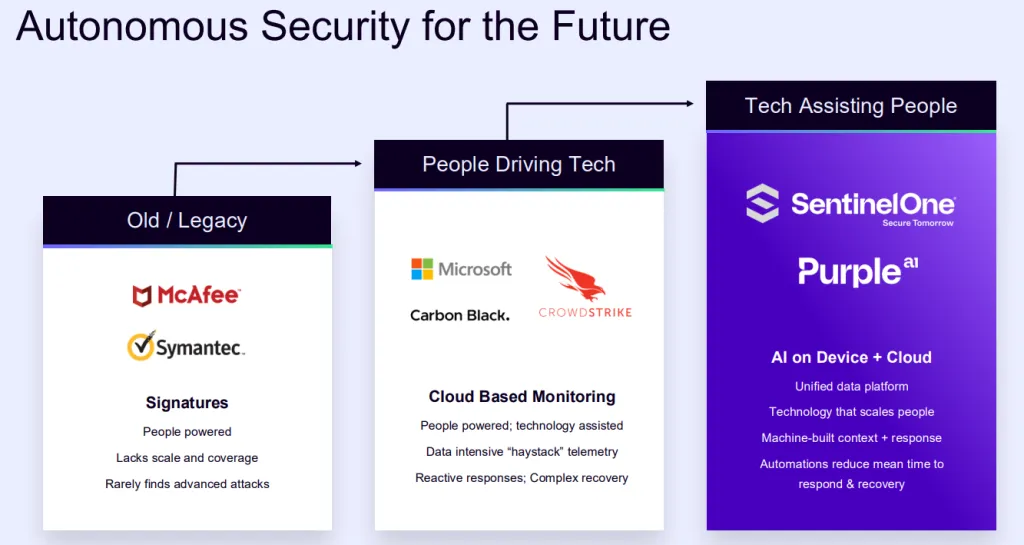
This is a playbook we’ve seen before: a smaller, more agile company leverages architecture, speed, and cost advantage to take share from a larger incumbent that’s slower to adapt. SentinelOne isn’t there yet, but it’s playing the right game.
Macro Isolation: Tariffs and the Clean Bubble
When tariffs returned in April 2025, equity markets re-priced risk overnight. SentinelOne barely flinched.
It has no hardware exposure, no global supply chain sensitivity, and no reliance on cross-border inventory flow. This kind of model, pure software, asset-light, mission-critical, offers protection when geopolitical noise escalates.
While global manufacturers and consumer brands react to macro headlines, SentinelOne keeps shipping product.
Post-Hype Opportunity: Where Real Setups Start
Cybersecurity had its hype cycle. 2021 was frothy. 2023 was the correction. Today, most of the names still standing are either overpriced or misunderstood. SentinelOne falls into the second category.
As capital flows rotate into “sure things,” the mispriced resilience of names like this creates asymmetric setups, especially when supported by actual results. Post-hype doesn’t mean post-potential.
Market Skepticism: What the Street Isn’t Seeing
After SentinelOne issued a conservative full-year forecast in March 2025, shares sold off. The numbers weren’t bad, just not explosive.
According to Reuters, the company still guided for nearly 27 percent ARR growth while improving margins. That isn’t a stumble. It’s a reset. One that leaves room for multiple expansion when execution continues.
This is often how inflection points form, not through wild beats, but through underappreciated consistency. When investors stop paying attention to a name that keeps performing, the opportunity grows.
Risks and Reassessment Triggers
We’re not immune to blind spots. Our thesis will change if:
- ARR growth falls below 20 percent
- The platform’s differentiation erodes
- AI-native security becomes commoditized or leapfrogged by better architecture
Additionally, we’re watching product velocity and customer mix closely. If SentinelOne slows its enterprise traction or over-indexes on SMBs without durable expansion, the thesis needs revision.
From Misunderstood to Necessary
National security is no longer confined to traditional battlefields; it now extends across digital networks, orbital infrastructure, and interconnected global systems.
SentinelOne isn’t priced like a winner. That’s what makes it interesting. We don’t need perfection. We want clarity, traction, and a credible path to structural relevance. SentinelOne is already showing signs of that path, without demanding a premium for it.
The best long-term positions rarely begin with full consensus. They begin when conviction is higher than visibility. And right now, SentinelOne is showing its cards even if the market isn’t watching.

Celsius Stock Analysis: The Shelf Reset and the Second Growth Curve
Celsius stock analysis of the shelf reset, Alani growth, Pepsi economics and cash flow, with a 2030 model and a Premium valuation and entry-price framework.

Meta AI Spending: The Customer Is Already Here
Can Meta turn AI spending into shareholder returns? We model advertising, Muse, hardware, capital costs and cash flow through 2030, with a full valuation.

IREN Stock Dilution: Can the Build Reach Shareholders?
IREN stock analysis of AI growth, funding and dilution through 2030. Read our full valuation, 27 scenarios and price zones free. Excel model is Premium.
Northwise Portfolios
See how the research becomes real decisions
Reader discussion
Discuss the research
Create a Free account to join the discussion with a display name.
Create a Free Account
No comments yet. Start a thoughtful discussion.