
Estée Lauder Stock Forecast
Estée Lauder stock forecast for 2025: Deep dive into valuation, recovery risks, Burry's big bet and why we believe the brand is being mispriced.
In this article
Estée Lauder Stock Forecast: Can the Beauty Giant Recover in 2025?
Prestige powerhouse or value trap? We dig deep into Estée Lauder’s fall and future.
Who Is Estée Lauder?
Estée Lauder Companies Inc. is one of the world’s largest and most iconic beauty businesses. Founded in 1946, the company has evolved into a global powerhouse with a brand portfolio spanning skincare, makeup, fragrance, and haircare. Its flagship names include MAC, La Mer, Clinique, Jo Malone, Tom Ford Beauty, and of course, Estée Lauder itself.
The business generates more than $15 billion in annual revenue and operates in over 150 countries. Historically, its growth has been driven by prestige positioning, deep wholesale and travel retail channels, and a strong footprint in Asia, especially China. But a combination of macro headwinds and strategic missteps has recently put the company on its back foot.
From a cultural icon to a recovery play, Estée Lauder now finds itself at a critical inflection point.
Why Estée Lauder Demands a Second Look
Estée Lauder has been battered. From pandemic whiplash to China volatility, few global giants have seen sentiment flip as hard or as fast.
But at $65, Estée Lauder is no longer a luxury darling. It is a misunderstood value reset, trading at less than half its 2021 highs. Michael Burry just doubled his stake. A new CEO is slashing $1B in costs. And one of the most powerful brand portfolios in global beauty is quietly retooling for the next cycle.
This is not about catching a falling knife. This Estée Lauder stock forecast is about asking if enough pain has been priced in.
The Fall of a Giant: What Went Wrong
Estée Lauder’s core strategy was built on two pillars: global travel retail and explosive China skincare growth. When both cracked, the floor fell out.
China softness and Hainan overstocking destroyed visibility and profit margins.
Inventory missteps post-COVID led to deep discounting and credibility loss.
FY25 sales are now projected to decline 8 to 9 percent, with EPS expected to land between $1.30 and $1.55.
Legacy strength met cyclical pain. Add margin pressure, Gen Z brand drift, and supply chain wounds, and you get a 60 percent stock price collapse.
Inside the Rebuild: Cost Cuts, Strategy Shifts, and Stabilization
Under new CEO Stéphane de La Faverie, the company is undertaking a full operational reset.
Laying off 7,000 employees Launching a $1 billion cost-reduction plan by 2026 Rebuilding inventory forecasting and margin discipline Expanding digital sales through Amazon and TikTok Shop
Early signs are promising. Gross margins have already improved from 72 percent to 75 percent, and Q1 earnings came in ahead of expectations with $0.65 EPS versus $0.31 estimated.
The Clean Beauty Shift: How Estée Lauder Is Responding
One of the most underappreciated risks facing Estée Lauder is not just macro, it is cultural.
In the last decade, the rise of clean beauty, ingredient transparency, and mission-driven indie brands has reshaped the beauty landscape. Younger consumers are gravitating toward brands like Drunk Elephant, Youth to the People, and Summer Fridays, built around authenticity, minimalism, and sustainability.
Estée Lauder has not ignored this shift, but their response has been measured and largely portfolio-driven rather than structural.
Strategic Acquisitions Over Internal Rebuild
Key to our Estée Lauder stock forecast, rather than radically reforming legacy labels, Estée has opted to buy its way into this trend:
Acquired Deciem, the parent company of The Ordinary Invested in Have and Be Co. known for Korean clean beauty brand Dr. Jart+ Acquired Too Faced and Le Labo which play well with millennial and Gen Z consumers focused on cruelty-free and clean formulations
Product Innovation Inside Legacy Brands
EL is also modernizing formulations and messaging across its flagship lines:
MAC and Estée Lauder have leaned into no-makeup makeup campaigns and cruelty-free certifications La Mer is introducing more ingredient traceability and sustainability disclosures Clinique has repositioned around dermatologist-approved, allergy-tested, fragrance-free products
DTC and Social Listening Channels
Estée Lauder is expanding on TikTok Shop and Amazon Premium to meet consumers where discovery happens They are building out DTC experiences around specific brands, enabling faster feedback loops and SKU testing
Compared to native DTC brands who live and breathe this language, Estée’s machine can feel slow. That said, its scale gives it leverage. If it gets the formula right, rollouts can happen globally and fast.
Why EL Could Be a Deep Value Rebound
A core piece to our Estée Lauder stock forecast: Iconic brand strength. MAC, La Mer, Tom Ford, Jo Malone. These are cultural staples with pricing power and global reach Travel retail and China normalization.
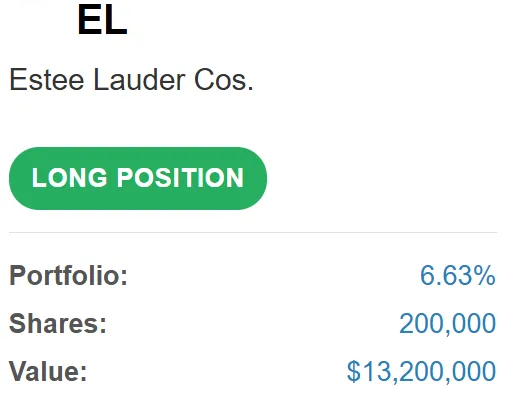
Even a partial rebound in Asia could dramatically shift earnings over a multi-year horizon Gross margin recovery is already underway and accelerating Digital and DTC growth is finally becoming a priority Michael Burry just doubled his position. Now holding 200,000 shares
This is not about fast growth. It is about operating leverage and brand stickiness resetting the base.
Why the Pain Might Not Be Over
China may not bounce back. Youth unemployment, property drag, and brand fatigue could structurally cap upside Gen Z drift is real.
DTC brands and clean labels are chipping away at Estée’s cultural edge Valuation still looks stretched on FY25 numbers. Around 40x depressed earnings with no near-term EPS catalyst Execution risk is high during a full global reset
This could easily turn into a multi-year grind, not a clean turnaround.
Estée Lauder Stock Forecast
At $65 per share, Estée Lauder trades near its 10-year low. While not cheap on forward earnings, the setup is increasingly asymmetric.
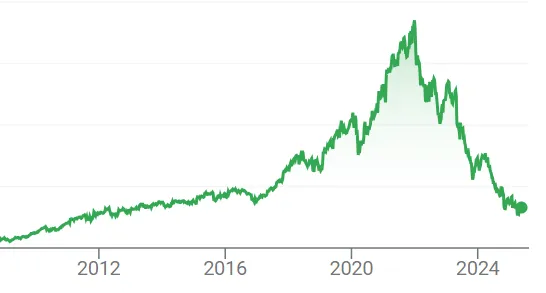
2025E EPS: $1.45 midpoint → 44x multiple 2026E EPS: If EL rebounds to $4 to $5 EPS → 13 to 16x forward P/E
That path likely depends on a China rebound and cost control landing. But if it does, this could rerate quickly into the $100 to $130 range, offering 50 percent or more upside from here.
A Fragile Reset With Durable Potential
Estée Lauder is not in crisis, but it is in transition. The business has taken real hits, both operationally and reputationally. But beneath that pain sits a global portfolio of brands that still command trust, pricing power, and cultural relevance.
The path forward will not be linear. China remains uncertain, Gen Z will not come back easily, and restructuring execution must be flawless. But the market has already priced in a good deal of that risk. What remains is a story of optionality. If even part of the turnaround thesis holds, EL is trading below its long-term value.
This Estée Lauder stock forecast is not curtailed for momentum chasers. It is for long-term investors willing to be early to a recovery, not late to a rerate.

Celsius Stock Analysis: The Shelf Reset and the Second Growth Curve
Celsius stock analysis of the shelf reset, Alani growth, Pepsi economics and cash flow, with a 2030 model and a Premium valuation and entry-price framework.

Meta AI Spending: The Customer Is Already Here
Can Meta turn AI spending into shareholder returns? We model advertising, Muse, hardware, capital costs and cash flow through 2030, with a full valuation.

IREN Stock Dilution: Can the Build Reach Shareholders?
IREN stock analysis of AI growth, funding and dilution through 2030. Read our full valuation, 27 scenarios and price zones free. Excel model is Premium.
Northwise Portfolios
See how the research becomes real decisions
Reader discussion
Discuss the research
Create a Free account to join the discussion with a display name.
Create a Free Account
No comments yet. Start a thoughtful discussion.