
Cheesecake Factory Stock
Cake Stock Forecast based on cash flow, hidden growth brands, and why the market’s narrative doesn’t match the numbers.
In this article
Cake Stock Forecast 2030: Mispriced Cash Flows and Growth
A thesis on optionality, margin resilience, dividend potential, and durable value hidden in plain sight.
Why Cheesecake, Why Now
This isn’t just about casual dining. It’s about the kind of corporate structure that invites misunderstanding. It’s about the valuation penalties assigned to legacy optics, and how certain businesses quietly evolve beneath the surface while the market keeps pricing the past.
Cheesecake Factory (CAKE) is one of the most misread names in consumer today, and the reasons why are both structural and psychological.
The narrative is tired: bloated menus, mall locations, aging demographics. But that narrative doesn’t hold up against the balance sheet, the margins, or the forward strategy. What we see instead is a brand operating multiple plays at once: cash flow stability, real estate leverage, and stealth growth through highly strategic acquisitions.
We’re not making a case for excitement. We’re making a case for mispricing, and in a market where capital is starved for yield and defensible growth, that’s what matters most.
Cheesecake Factory Stock as a Static Story
Most investors still view CAKE through a 2015 lens: a mid-market chain with oversized portions and oversized square footage. The logic seems fair; consumer dining preferences have shifted, food inflation pressures persist, and mall foot traffic remains uneven. But that view misses several key pivots.
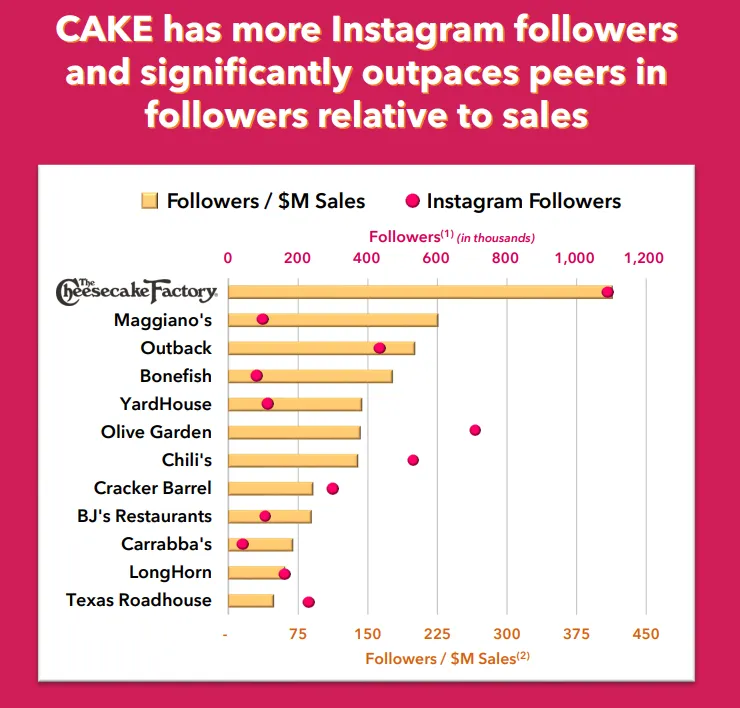
The Cheesecake brand has sustained traffic in high-income urban markets. Its pricing power has kept pace with inflation. And its loyalty loop, birthday dinners, group events, impulse cheesecake slices, hasn’t cracked, even post-pandemic. But even that’s not the full story.
What isn’t getting priced in is the fact that CAKE today isn’t just CAKE. It’s a portfolio.
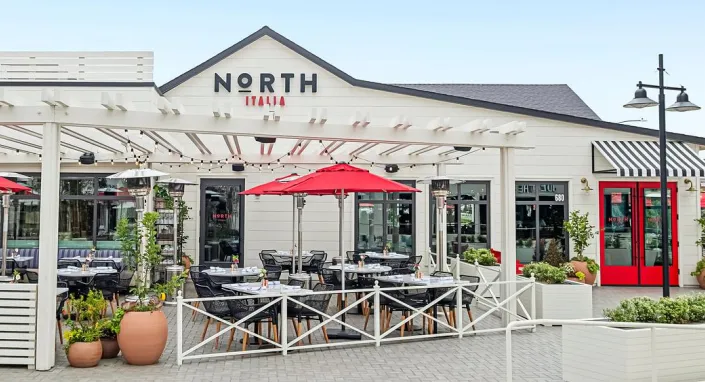
The Real Growth Engine: North Italia & Flower Child
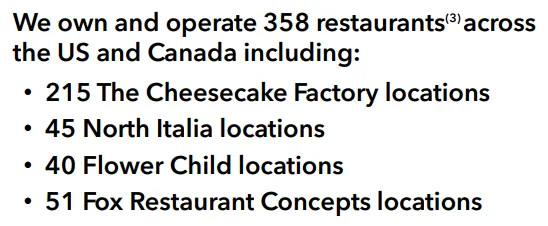
North Italia and Flower Child, acquired through the Fox Restaurant Concepts deal, are now core to the company’s expansion plans, not side bets.
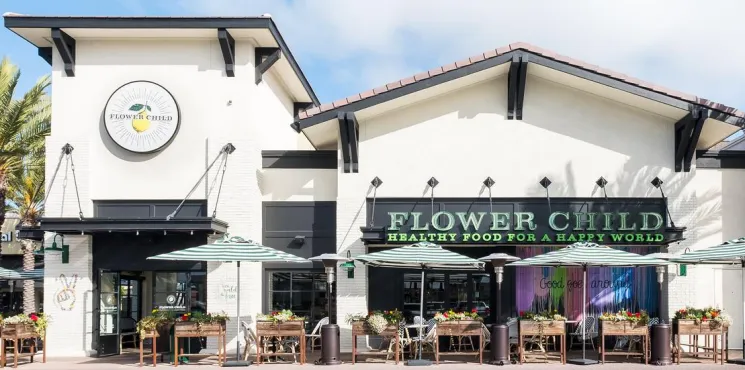
In Q4 2024, North Italia delivered 7.6% comp growth and strong unit economics across multiple regions. Flower Child, with its fresh-forward menu and minimal-waste kitchen model, is built for scalable health-conscious dining. Both brands play to modern preferences: smaller formats, curated menus, lifestyle alignment.
These aren’t experimental concepts. They’re scaled, proof-tested growth levers. And they attract a demographic CAKE never did: younger, wellness-driven, urban-professional consumers.
If you break them out, they likely deserve a growth multiple on their own. Instead, they’re buried inside a blended Cheesecake valuation.
“We remain focused on expanding our growth concepts, North Italia and Flower Child, where we continue to see significant whitespace opportunity.” – Cake Q4 2024 Earnings
Cash Flow, Discipline, and Return Potential
Cheesecake Factory generated $3.5B in revenue in FY2024, producing $121.4M in GAAP net income. They’ve reinstated their dividend and resumed share repurchases, both signals of internal confidence and operational consistency.
But the more important detail isn’t just the yield. It’s the quality of the return. This isn’t a levered, defensive capital structure throwing off yield to mask a decline. This is a company with stable operations, a moderate growth engine, and the ability to both reinvest and return capital without compromise.
As North Italia and Flower Child grow, margins are expected to expand. Capital expenditure per unit is lower than the Cheesecake core model, and once the concepts hit scale, the math shifts fast.
Over time, this opens the door to substantial dividend increases, particularly if legacy cash flows stay steady.
A Balance Sheet That Allows for Asymmetry
The best optionality often hides behind clean financials.
CAKE enters 2025 with:
- Low net leverage
- Strong lease positioning
- Conservative, well-timed capital allocation
- A defensive moat built on real estate and loyal foot traffic
This isn’t a speculative recovery story. It’s a cash-flowing operator with financial room to be patient and opportunistic.
That matters in a market where many competitors are still overextended or constrained.
Misunderstood by Design
This is where it gets interesting. CAKE still trades at a multiple consistent with casual dining peers: many of which don’t own differentiated brands, or the capacity to scale.
Cheesecake’s strength is misunderstood because the structure is familiar, and the growth is embedded.
What happens when a real estate-backed cash flow machine quietly starts compounding with modern margin structures? Most investors don’t notice. Until the payout ratio spikes, or comps break out, or the Street gets forced to remodel the brand.
We’re early. But we’re paying attention.
What Could Derail the Execution
None of this is risk-free. We’re not in the business of ignoring downside; we’re in the business of measuring it.
- Poor execution on the rollout of North Italia or Flower Child
- Margin compression due to labor costs or commodity price spikes
- A reversion to overly cautious or defensive capital allocation
- If the market remains unwilling to reprice the portfolio correctly
If the strategic execution falters (especially around North Italia or Flower Child) the optionality narrative loses its engine. If labor or food costs accelerate faster than expected and outpace pricing power, margin expansion could stall.
There’s also the real risk of misalignment at the executive level. If management reverts to a defensive capital strategy or fails to communicate the forward-looking vision to the market, it may delay or block a rerating altogether. Sentiment matters, even in value.
And then there’s valuation inertia. The market might simply refuse to reprice the Cheesecake portfolio, even if the numbers support it. That’s the cost of being embedded inside a legacy brand story.
But at this price, the asymmetry still favors patience. The risk isn’t zero; it’s just contained.
Why We’re Watching CAKE in 2025
This is a business being valued on what it was, not on what it’s becoming. That delta is the entire opportunity.
Cheesecake Factory is quietly running a blended portfolio with strong free cash flow, low net leverage, and two growth brands that are comping well above industry averages. If they execute even moderately well, the gap between perception and structure will close. And when that gap closes, rerating tends to follow.
It doesn’t need hype. It doesn’t need a pivot. It just needs to keep doing what it’s doing, with slightly better storytelling and continued operational control. We believe CAKE can deliver that.
The reason we’re watching isn’t because it’s exciting. It’s because it’s stable, expanding, and misunderstood, and those three things, together, often create a durable edge.
Let’s keep building.

Celsius Stock Analysis: The Shelf Reset and the Second Growth Curve
Celsius stock analysis of the shelf reset, Alani growth, Pepsi economics and cash flow, with a 2030 model and a Premium valuation and entry-price framework.

Meta AI Spending: The Customer Is Already Here
Can Meta turn AI spending into shareholder returns? We model advertising, Muse, hardware, capital costs and cash flow through 2030, with a full valuation.

IREN Stock Dilution: Can the Build Reach Shareholders?
IREN stock analysis of AI growth, funding and dilution through 2030. Read our full valuation, 27 scenarios and price zones free. Excel model is Premium.
Northwise Portfolios
See how the research becomes real decisions
Reader discussion
Discuss the research
Create a Free account to join the discussion with a display name.
Create a Free Account
No comments yet. Start a thoughtful discussion.