
HNST Stock Forecast 2030
HNST stock forecast 2030: Discover why The Honest Company’s transformation 2.0, profit focus, and clean balance sheet signal upside.
In this article
HNST Stock Forecast 2030: The Honest Company’s Path From Reset to Rebound
A deep analysis of The Honest Company’s 2030 growth potential, management’s Transformation 2.0 strategy, and why near-term volatility may mark the bottom for long-term investors.
Thesis Overview
The Honest Company’s turnaround is advancing in plain sight while the market looks the other way. After our original Northwise thesis projected a shift from top-line expansion to margin-led growth, that transition is now happening.
It arrived later than expected, yet it is following the same trajectory we outlined in 2025. The company has removed unprofitable categories, protected its balance sheet, and produced consistent profitability. Still, the stock trades near relative lows around $2.65 per share.
We now view Honest as one of the most undervalued names in consumer staples. Its strategic focus, clean financial structure, and accelerating core categories point to meaningful compounding potential through 2030. Our forecast anticipates a return to steady growth beginning in late 2026, expanding margins each year, and a fair value between $8 and $15 per share by the end of the decade.
For readers who missed the foundation of this view, revisit our earlier article The Honest Company Stock Forecast 2025. This new thesis extends that framework with fresh data, management commentary, and updated financial modeling through 2030.
HNST Stock Forecast 2030 and Investment Thesis
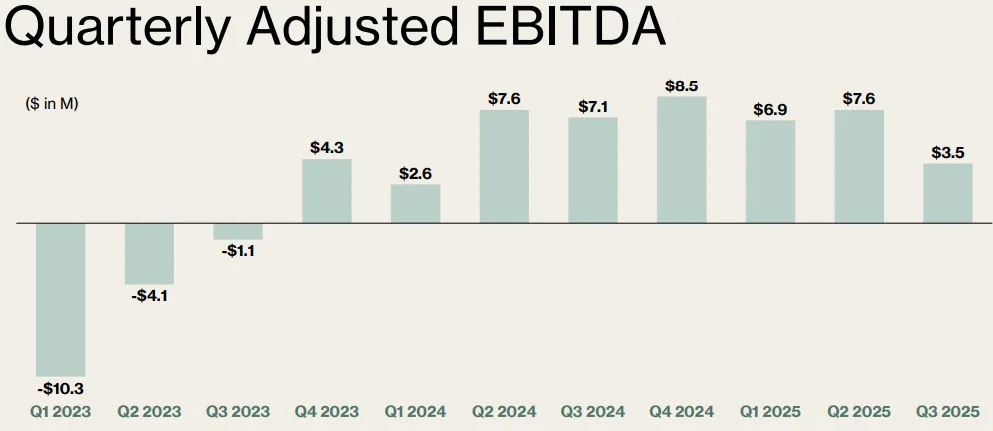
Honest’s Q3 2025 report confirmed that management is following a disciplined transformation plan. Revenue came in at $93 million, down 7 percent year over year, but gross margins held near 37 percent despite tariff costs and lower volumes. Net income reached $1 million, marking the company’s third consecutive quarter of profitability.
While diapers remain under pressure, wipes and baby personal care are expanding at double-digit rates and now make up more than half of total sales. Honest has $71 million in cash, no debt, and improving repeat purchase rates. In a consumer sector where heavy leverage and stagnant growth are common, that combination stands out.
The revenue contraction is not a warning sign. It reflects a deliberate pruning of low-margin business segments so that the company can redeploy capital toward profitable growth.
Transformation 2.0: Powering Honest Growth and Profitability
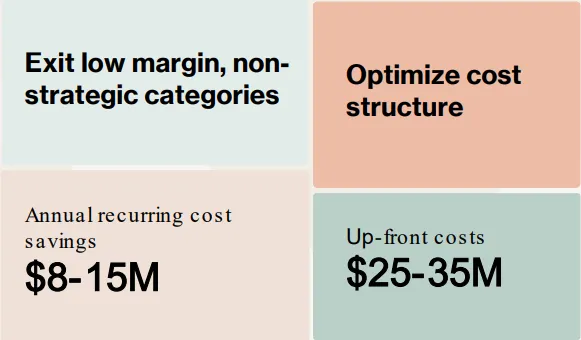
In late 2025, management launched Transformation 2.0: Powering Honest Growth, a full-scale operational reset designed to simplify the business and concentrate resources where Honest already wins. The initiative narrows focus to three categories: wipes, personal care, and diapers.
Chief Executive Officer Carla Vernon described the plan clearly:
“This new and important step allows us to sharpen our focus on growing the categories where we have a demonstrated right to win, while also improving the profitability of Honest.”
The exits include honest.com, the company’s direct fulfillment site, the Canadian retail channel, and the apparel line.
Chief Financial Officer Curtiss Bruce said:
“the plan will incur one-time transformation costs of $25 to $35 million, producing $8 to $15 million in annual savings beginning in 2026.”
Bruce noted, “We will start seeing expenses related to the transformation program in Q4 and then the savings beginning in 2026.” This timing indicates that 2026 will be the final adjustment year before normalized growth returns.
By removing complexity and consolidating operations around high-margin products, Honest is setting up a leaner, higher-return structure. The company is intentionally trading scale for quality of earnings.
Why Turnarounds Like Honest Co Get Mispriced
Investors routinely undervalue companies midway through turnarounds. When revenue starts falling, sentiment often collapses even when that drop is strategic. Honest’s price action fits that pattern.
This is the stage of the cycle where market algorithms and fund screens see only a declining top line, while patient investors recognize the compounding potential that follows. As Vernon put it, “We continue to grow and outpace the market in our wipes and personal care categories.” Those are the lines that define Honest’s long-term profitability.
Mix Economics and Core Strength
Honest’s mix shift is quietly improving the business even before new growth arrives. Wipes, now representing more than one third of sales, saw consumption rise 24 percent year over year. Baby personal care rose 10 percent, maintaining Honest’s position as the number one natural baby care brand in the United States.
Product quality and customer satisfaction are improving. “Our diaper consumer complaints are down 21 percent versus last year,” Vernon told investors. Price adjustments and smaller pack sizes at Walmart and Amazon are also improving sell-through.
By cutting roughly one fifth of low-margin revenue while retaining the high-margin categories, Honest is raising gross profit potential even as total sales dip. The company is losing its least valuable revenue first.
The Honest Company Financial Forecast Through 2030
The next year will close the transformation chapter. Reported revenue will likely remain soft through early 2026, followed by steady expansion through 2030 as cost savings and mix improvements take hold.
Forecasting Framework and Key Assumptions
Our updated model uses fiscal 2025 as the reset base. The core assumptions are:
- Revenue declines continue through early 2026 due to the 20 percent business exit.
- Annual cost savings of $8 to $15 million begin mid-2026.
- Revenue growth averages 5 to 10 percent per year from 2027 through 2030, driven by wipes and personal care.
- Gross margin rises from 38 percent to between 42 and 44 percent as product mix improves.
- Free cash flow margin reaches 6 to 9 percent by 2030.
- Terminal valuation multiples range from 20x to 25x forward earnings.
- Weighted average cost of capital is 10 percent, terminal growth rate 3 percent.
Bear Case
Metric | 2025E | 2026E | 2030E |
|---|---|---|---|
Revenue | $382M | $370M | $450M |
Gross Margin | 38% | 38% | 40% |
Net Margin | 1.8% | 2% | 3% |
EPS | $0.06 | $0.07 | $0.15 |
FCF Margin | 0% | 1% | 3% |
If diaper recovery is slow and macro headwinds persist, Honest still produces positive free cash flow and could trade near $4 to $6 by 2030.
Base Case
Metric | 2025E | 2026E | 2030E |
|---|---|---|---|
Revenue | $382M | $377M | $520M |
Gross Margin | 38.5% | 38% | 42% |
Net Margin | 1.8% | 2% | 6% |
EPS | $0.06 | $0.07 | $0.35 |
FCF Margin | 0% | 1% | 6% |
Steady execution and cost savings yield mid-single-digit revenue growth and margin expansion toward a valuation range of $8 to $10 per share by 2030.
Bull Case
Metric | 2025E | 2026E | 2030E |
|---|---|---|---|
Revenue | $382M | $380M | $672M |
Gross Margin | 39% | 39.5% | 43% |
Net Margin | 2% | 2.5% | 8% |
EPS | $0.07 | $0.08 | $0.55 |
FCF Margin | 1% | 2% | 8% |
Improving diaper performance and wider retail distribution lift growth toward an 8 to 10 percent CAGR, supporting valuations between $12 and $15 per share.
Stretch Case
Metric | 2025E | 2026E | 2030E |
|---|---|---|---|
Revenue | $382M | $385M | $900M |
Gross Margin | 39% | 40% | 44% |
Net Margin | 2.5% | 3% | 10% |
EPS | $0.07 | $0.09 | $0.80 |
FCF Margin | 2% | 3% | 9% |
A partnership, acquisition, or international re-entry adds leverage to the model. At 12 to 15 percent growth, Honest could command a price between $18 and $22 per share by 2030.
Is The Honest Company Preparing for an Acquisition?
Honest’s current structure appears tailored for acquisition. The company has no debt, $71 million in cash, and all major categories operating profitably. A clean balance sheet and focused product mix make it easy to integrate into a larger consumer portfolio.
Potential suitors include Procter & Gamble, Unilever, and Amazon, each of which could gain immediate exposure to Honest’s clean-label brand equity. Comparable transactions for small profitable brands often occur at 1.5 to 2.5 times sales. That multiple range implies a share price between $5 and $9 without any assumption of further growth.
The Honest Company Financial Ratios and Industry Comparison
Honest’s balance sheet remains one of the cleanest in the consumer staples sector. The company has no debt, $71 million in cash, and strong liquidity with a current ratio of 4.8. This conservative structure gives Honest flexibility to fund growth internally and navigate short-term tariff or supply shocks.
At roughly $2.65 per share, Honest’s market capitalization sits near $286 million. With trailing twelve-month revenue of about $390 million, the stock trades at less than 0.8 times sales: a valuation level typically reserved for distressed firms, not profitable ones.
The table below compares Honest’s key valuation and profitability ratios against leading peers in the consumer staples category.
Metric | HNST | (PG) | (KMB) | Industry |
|---|---|---|---|---|
Trailing P/E | 43.5 | 25.4 | 18.2 | 22.5 |
Forward P/E | 18.8 | 22.1 | 16.8 | 19.0 |
Price-to-Sales | 0.76 | 4.8 | 2.1 | 2.5 |
Debt/Equity | 3.4% | 62% | 145% | 80% |
Gross Margin | 39% | 50% | 35% | 35% |
Net Margin | 1.9% | 18% | 10% | 8% |
Honest’s valuation is far below the peer group on every major multiple, while its balance sheet is nearly debt-free. The company’s gross margins are now above the industry average, and its net margin has turned positive, marking a dramatic improvement from losses only two years ago.
This disconnect highlights how sentiment lags fundamentals. If Honest’s profitability continues to scale and margins expand toward 6 to 8 percent by 2030, a rerating toward 1.5 to 2.0 times sales would not be speculative.
Why Honest Stock Is a Good Deal Today
At a market capitalization below $300 million and a price-to-sales ratio under one, Honest is priced as if its turnaround has already failed. Investors are essentially paying for the tangible assets and receiving the brand, distribution, and IP at no cost.
Honest’s leadership team has proven operational discipline, its product categories are expanding, and its capital position remains strong. The fundamentals are improving while sentiment is near all-time lows. Historically, these are the conditions that precede the sharpest re-ratings.
For investors who can tolerate short-term noise, the next 12 to 18 months represent the bridge from restructuring to compounding. Honest’s fundamentals suggest this is a rare opportunity to own a profitable clean-label brand before the market reappraises it.
HNST Stock Forecast 2030: Long-Term Upside and Final Take
We expect 2026 to mark the bottom of reported revenue and the turning point for operating leverage. The company’s cost savings, improving category mix, and disciplined capital structure set the stage for a decade of profitable growth.
Honest’s valuation today prices in failure. The data show resilience. The next phase of compounding will reward patience.
Honest Company Stock Forecast
Honest Company stock forecast 2025 reveals a profitable turnaround driven by margin expansion, retail strength, and disciplined brand execution.

Celsius Stock Analysis: The Shelf Reset and the Second Growth Curve
Celsius stock analysis of the shelf reset, Alani growth, Pepsi economics and cash flow, with a 2030 model and a Premium valuation and entry-price framework.

Meta AI Spending: The Customer Is Already Here
Can Meta turn AI spending into shareholder returns? We model advertising, Muse, hardware, capital costs and cash flow through 2030, with a full valuation.
Northwise Portfolios
See how the research becomes real decisions
Reader discussion
Discuss the research
Create a Free account to join the discussion with a display name.
Create a Free Account
No comments yet. Start a thoughtful discussion.