Jumia Nigeria Analysis
Jumia Nigeria: the latest marketplace growth, revenue contribution, delivery economics and limits of the public country disclosure.
In this article
Nigeria is one of Jumia's most consequential markets because it combines a large commercial opportunity with the practical demands of acquiring customers, moving goods and collecting payment across a broad service area. The latest operating update supports continued growth, but that growth still needs to become durable cash contribution.
This country study sits within the Jumia market-by-market guide, which compares the current eight-market footprint on a consistent reporting basis.
The latest reported business
Reported revenue, USD millions | Q2 2025 | Q2 2026 |
|---|---|---|
Nigeria | 9.680 | 11.893 |
Source: Jumia's June-quarter geographical revenue note. The operating release separately reports Nigeria GMV growth of 36% and order growth of 34% year over year.
Those measures answer different questions. Orders count activity, GMV describes merchandise value, and revenue reflects the company's accounting for what it sells and the services it provides. Their growth rates need not match.
Scale has to produce successful deliveries
The operating advantage of a larger marketplace comes from making a network more productive. More demand near an existing route can reduce the delivery cost per order. More orders scattered across expensive new routes may not. That makes the location and reliability of demand as important as the national total.
Pickup stations can help consolidate delivery destinations, but they also require customers to complete collection. A successful order needs the product to be available, the package to arrive and the customer to accept it. A larger order book with more cancellations or failed collections would be a weaker outcome than the headline suggests.
This is the mechanism behind the Nigeria investment case. The country offers room to spread logistics and platform costs over more commerce. It does not remove the need to measure those costs.
Affordability and payment options
Jumia's 2024 Easybuy and CredPal announcement documents a route to instalment payments through external partners. It is historical evidence of the offering, not a current guarantee that every customer or item qualifies on identical terms.
Credit can help a customer afford a purchase, but the allocation of lending risk matters. A checkout partnership should not automatically be described as a Jumia-owned lending book. Nor does easier access to finance prove that the resulting sales are profitable after partner charges, servicing costs and returns.
The quality of growth
For Nigeria, repeat purchasing is more informative than a single successful promotion. A customer who returns because the service is useful can be more valuable than one who only buys under a large subsidy. A broader seller range helps when it improves availability and trust, rather than simply adding listings that do not convert.
Currency translation is another boundary. Dollar revenue can move for reasons that differ from local-currency shopping activity. Reported figures, constant-currency measures and management commentary should be read together when evaluating the trend.
What would strengthen the case
The next useful evidence is continued order growth with reliable delivery, repeat customers, healthy marketplace monetization and controlled fulfilment costs. Country revenue alone does not disclose Nigeria's stand-alone profit or its complete allocation of group expenses.
Nigeria provides an important test of whether Jumia's operating system can scale. The group model report examines what that would mean financially, and Jumia coverage links the other country studies.
Jumia Stock Forecast 2030: The Business Beyond Breakeven
Explore Northwise’s Jumia stock forecast for 2030: country growth, unit economics, cash flow, dilution and three valuation scenarios, with a financial model.
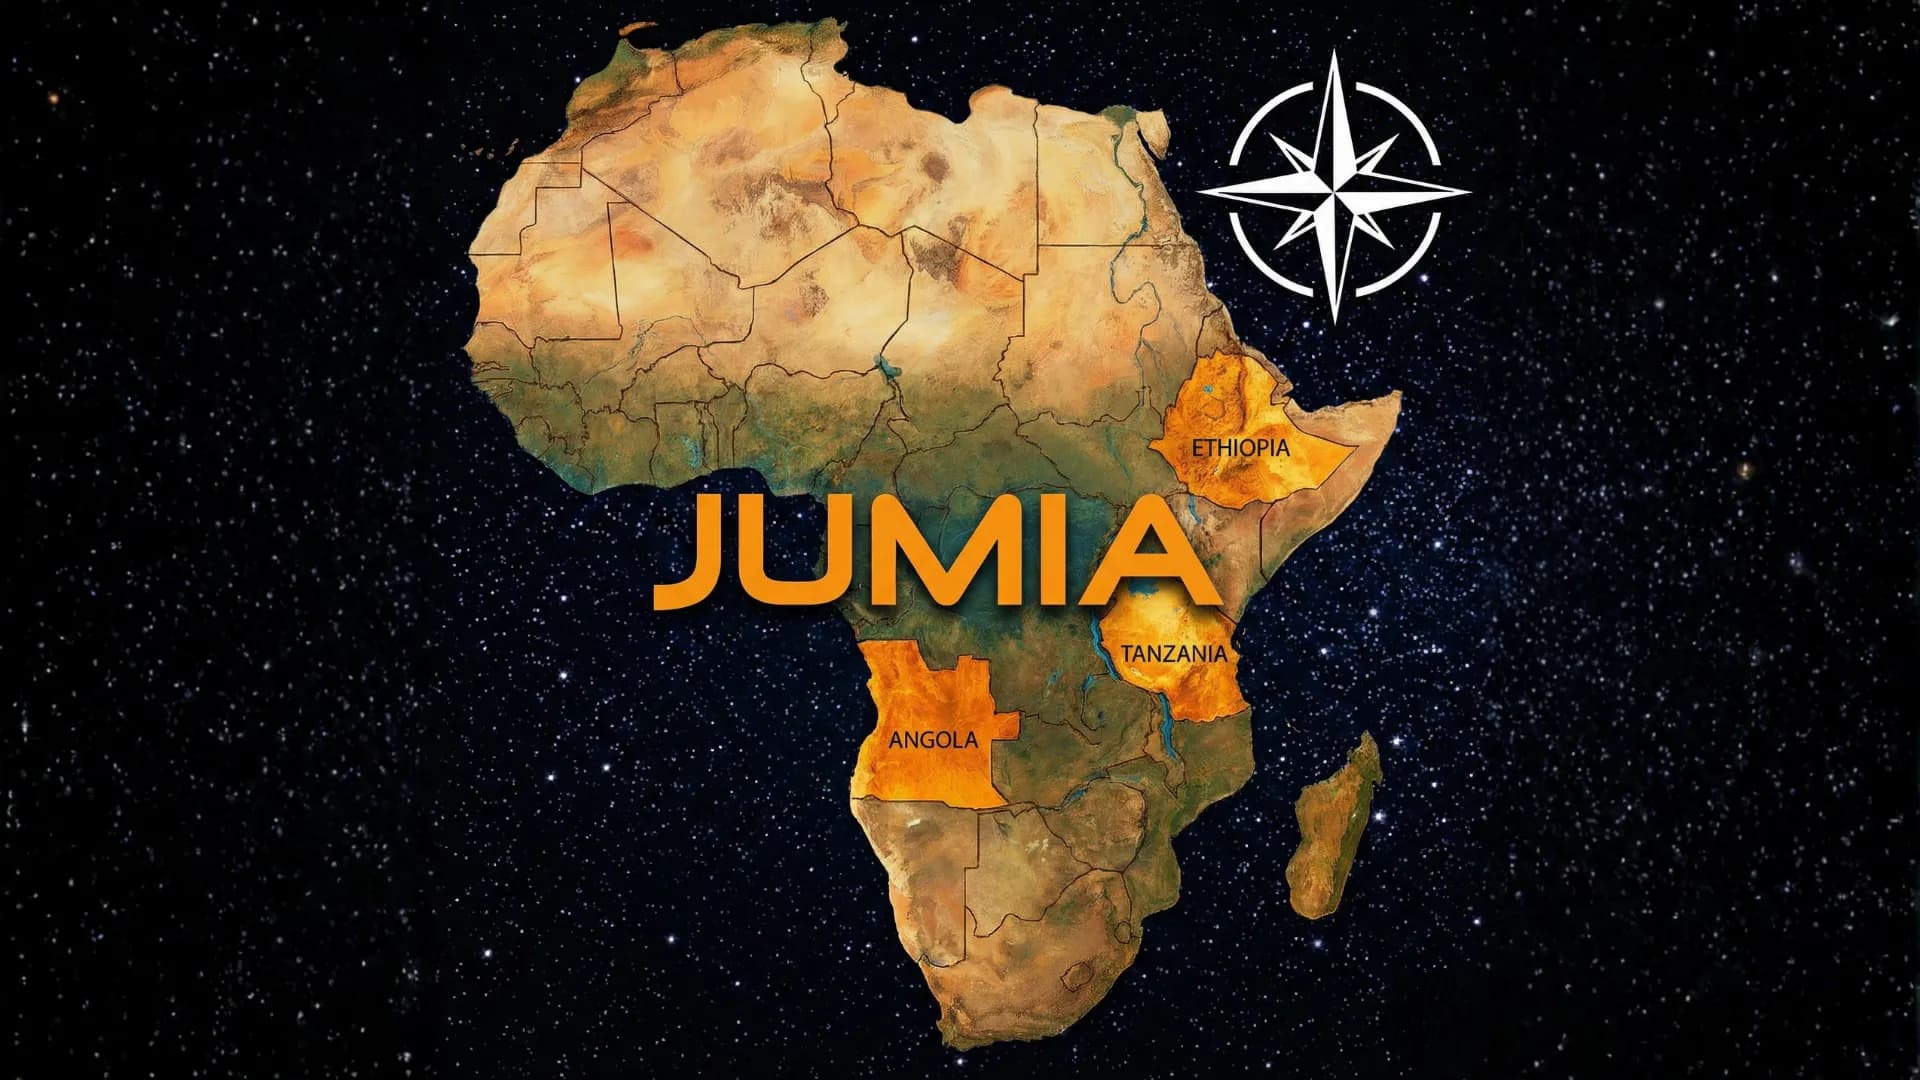
Where Will Jumia Expand Next?
Where will Jumia expand next after profitability? We examine Tanzania, Angola, and Ethiopia as post-2027 growth options.

Jumia Uganda
Jumia Uganda: a growing revenue contribution from a smaller base, customer retention and the economics of expanding delivery coverage.
Northwise Portfolios
See how the research becomes real decisions
Reader discussion
Discuss the research
Create a Free account to join the discussion with a display name.
Create a Free Account
No comments yet. Start a thoughtful discussion.